Key Takeaways
- Many Tampa Bay homes still need major repairs after recent hurricane seasons, and banks are often reluctant to finance them.
- Short-term, asset-based loans let investors buy and renovate properties a traditional lender will not touch.
- Flood zone rules, insurance, and repair timelines can make or break the numbers.
- These loans cost more than a mortgage, so a clear plan to sell or refinance is essential.
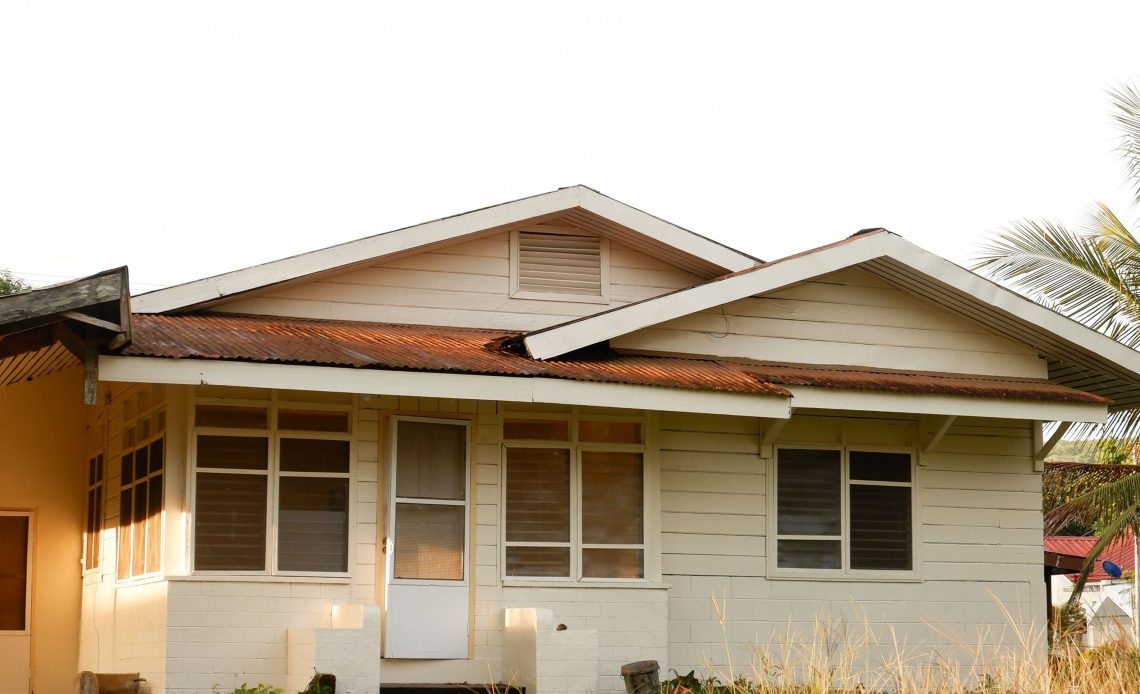
Drive through parts of Pinellas County, South Tampa, or the Hillsborough County coastline, and you will still spot blue tarps, gutted garages, and “For Sale As-Is” signs. Hurricanes Helene and Milton hit the region back to back in the fall of 2024, and some owners decided to sell rather than rebuild.
For investors, that has created opportunity. It has also created a financing problem.
Why Banks Shy Away From Damaged Properties
Conventional lenders want a house that is safe, insurable, and livable on closing day. A home with a leaking roof, missing drywall, or water-damaged electrical systems usually fails that test.
Even if the buyer has strong credit, the property itself can sink the application. Appraisers flag the damage, underwriters ask for repairs before funding, and the seller is not about to fix a house they are trying to unload.
That leaves buyers stuck. The deal looks great on paper, but no bank will close on it.
How Investors Get These Deals Done
This is where hard money comes in. Instead of judging the borrower mainly on income and credit, a hard money lender looks at the value of the real estate, the equity in the deal, and how the investor plans to get out of the loan.
Speed is a big part of the appeal. Distressed properties tend to sell quickly, often to the first buyer who can close. Local lenders offering Tampa hard money loans, such as Associates Home Loan of Florida, Inc. (NMLS 380601), say many of these deals can close in roughly one to two weeks, compared with a month or more for a typical bank loan.
Once the property is purchased and repaired, the investor usually sells it or refinances into a long-term mortgage, paying off the short-term loan in the process.
[Image 2: renovation crew installing new drywall and windows inside a gutted Florida home]
Tampa-Specific Issues to Plan For
Buying a storm-damaged home in Tampa Bay is not the same as buying a fixer-upper in most other markets. A few local factors can change the math quickly.
Flood zone rebuilding rules. In many flood-prone areas, local governments follow federal flood insurance rules that limit how much you can spend repairing a home before it has to be brought fully up to current flood standards. That threshold is often tied to 50 percent of the building’s market value. Crossing it can mean elevating the home or making other costly changes, so check with the city or county before you make an offer.
Insurance availability. Some older homes are hard or expensive to insure until the roof and other systems are updated. Get quotes early so insurance costs do not catch you off guard.
Contractor and permit timelines. Demand for roofers, electricians and inspectors can stretch schedules, especially after another active storm season. Build extra weeks into your plan.
Hurricane season itself. A half-finished renovation is vulnerable from June through November. Secure the building envelope first whenever possible.
What the Lender Wants to See
A fast approval still involves real scrutiny. Expect the lender to ask about:
- The purchase price and the property’s current condition
- A repair budget and scope of work
- The estimated value after repairs are finished
- Any existing liens on the property
- Your experience with similar projects and the cash you have in reserve
- Whether you plan to sell or refinance, and roughly when
The more equity in the deal, the more comfortable a lender will be. Borrowing a smaller share of the property’s value also leaves you with a buffer if repair costs run high.
Know the Costs Before You Commit
Hard money is a tool for speed and flexibility, not a cheap one. Rates run higher than conventional mortgages, and lenders typically charge points up front along with appraisal, title and closing fees. Many of these loans are interest-only, with the full principal due in one lump sum at the end.
That is why the exit plan matters so much. If repairs drag on, the market cools or a refinance falls through, carrying costs keep adding up. Ask for the full written terms, including any fees to extend the loan, and run the numbers with a cushion for delays.
Build Your Plan Before the Next Storm
Tampa Bay’s damaged homes can be a smart buy for investors who move quickly and plan carefully. The best results usually come from checking flood zone rules before making an offer, lining up insurance and contractors early and choosing a licensed Florida lender that explains every cost in writing.
Do that homework first, and a house most buyers would walk away from could become your next successful project.